Forex sentiment sample bias is the risk of treating a defined sentiment sample as though it represented the entire foreign exchange market.
That distinction is easy to overlook. A broker may publish information about its clients’ open positions or pending orders, and the presentation can look comprehensive. Yet the underlying observation still comes from a particular population, product set, legal entity, region, methodology and refresh process. It is not automatically a census of banks, corporations, asset managers, hedge funds, retail traders and other participants active across global FX markets.
This does not make broker sentiment data useless. It means the information must be labelled correctly before it is interpreted. A broker sample can help describe the behaviour of that broker’s clients. An order book can show where pending orders are distributed within the available sample. A position book can show how existing client exposure is arranged. Neither source, by itself, establishes the complete positioning of the market.
The central research habit is simple. Before asking what a sentiment reading means, ask whose activity it describes, what is being counted, when it was observed and what the source excludes. These checks help separate useful context from an overconfident market-wide conclusion.
Forex Sentiment Sample Bias: Define the Population
The first check is to define the population behind the observation. The phrase broker sentiment population should never be treated as a synonym for the FX market. It describes the clients and products included by a particular provider under a particular methodology.
That population may contain retail clients using a broker’s spot FX or CFD offering, sometimes across more than one legal entity within the same group. The exact scope depends on the provider’s documentation. Some sources describe broad client coverage, while others are limited by region, account type, instrument availability or data permissions.
A responsible reader asks whether the source identifies its entities, client coverage and participant mix. Retail clients are not interchangeable with banks, corporates, asset managers, hedge funds or futures traders, because each group can have different objectives, time horizons and execution arrangements. A retail positioning sample may still be useful, but it does not describe every participant.
This is the foundation of retail positioning sample bias. The issue is not necessarily an error in calculation. It is the gap between the defined sample and the broader population a reader may assume it represents.
The product matters as well. Spot FX is decentralised and traded across many venues, so a broker’s client data reflects only activity visible to that broker. Futures positioning belongs to a different reporting framework. The CFTC Commitments of Traders resource explains that scope, which can add context without becoming a complete view of OTC spot FX positioning.
A clear research note should state the population in plain language, such as positions visible within a broker-defined client sample. That is more precise than presenting the reading as though it described the entire market. If the source does not explain its scope, the right response is to reduce confidence and state the uncertainty.
A useful population checklist includes these questions:
- Which legal entities contribute the information?
- Which instruments and account types are included?
- Are the observations based on open positions, pending orders or both?
- Are dormant, demo, hedged or inactive accounts treated in a stated way?
- Does the provider explain the denominator and calculation method?
- Does the source identify any regional or product exclusions?
If those answers are not available, the correct response is not to infer them. The correct response is to reduce the strength of the conclusion and describe the uncertainty.
Forex Sentiment Sample Bias: Compare Like With Like
The second check is to compare like with like. A sentiment sample comparison becomes unreliable when the sources measure different populations, instruments, units or time windows.
An order book and a position book are the clearest example. An order book generally describes pending orders, while a position book describes existing open exposure. Those are different objects, so they answer different questions. A cluster of pending orders does not prove that clients are already positioned in the same direction, and a concentration of open positions does not reveal every order that might later be placed.
The distinction matters when reading an OANDA order book and position book. OANDA describes these tools as showing pending orders and open positions from the relevant client data set. That is useful transparency, but it does not make either tool a consolidated view of global FX activity.
The denominator matters too. A provider may describe a distribution across accounts, positions, orders or volume, and those measures are not interchangeable. Instrument definitions and timing also matter. A spot or CFD position is not the same as a currency futures position, and a broker snapshot should not be treated as though it were captured at the same time as a periodic report.
A disciplined sentiment sample comparison records the source, instrument, timestamp, time zone, refresh process, population and denominator. The goal is not complexity. It is enough structure to know whether the observations are genuinely comparable.
Consider the difference between saying that broker clients are positioned one way and saying that the market is positioned one way. The first describes a source-defined sample. The second makes a far broader claim that ordinary broker sentiment data usually cannot support on its own.
The same caution applies when comparing two brokers. Similar labels do not mean the samples are equivalent. Clients may trade different products, use different account structures or sit in different regions, and one source may update or exclude data differently from another.
The purpose of comparison is clarification, not forced agreement. If two sources diverge, check scope, timing and measurement before deciding that one must be wrong.
A good research record separates observation from interpretation:
- Observation, the provider reports a defined distribution of its client data.
- Scope, the provider identifies or limits the participating population.
- Timing, the information represents a particular observation window.
- Interpretation, the reading may describe crowd exposure within that sample.
- Limitation, the reading does not establish total market positioning.
This structure keeps forex sentiment sample bias visible instead of hiding it behind a confident label.
Retail Positioning Sample Bias and Broker Sentiment Population
The third check is to examine the relationship between retail positioning sample bias and the broker sentiment population.
Retail positioning data can be informative because it reveals how a defined group of clients is engaging with a market. It may show whether open exposure is concentrated in one direction or distributed more evenly. It may also provide context for understanding how pending orders and existing positions relate to one another.
But a retail sample is not a forecast. It does not prove that a majority position will be forced to close, that a crowded trade must reverse or that the wider market will move against those clients. Any such conclusion would add a predictive claim that the sample alone cannot support.
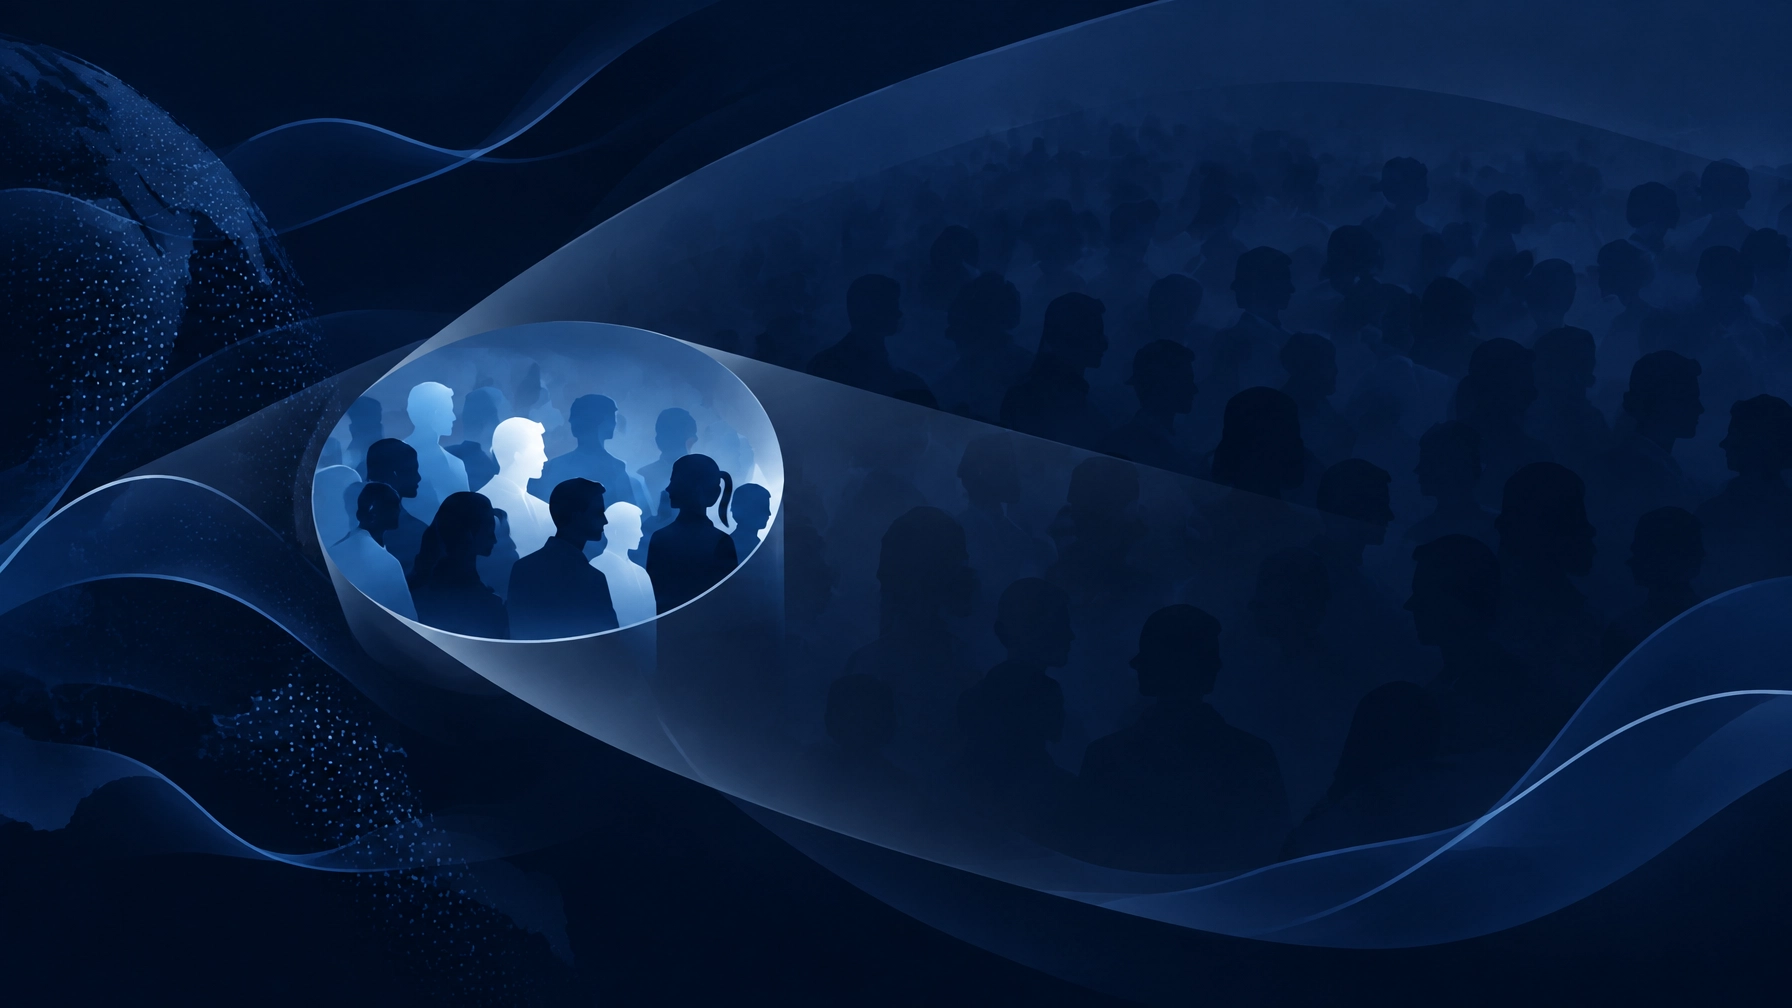
The broker sentiment population may have behavioural characteristics that influence the reading. Clients can differ in trading frequency, holding period, risk tolerance and use of stops, and the data can change as accounts open, close or shift exposure between instruments.
Retail behaviour can also vary for reasons unrelated to any broad market consensus. Some clients may be reacting to volatility, some may be adding to existing exposure and others may be hedging elsewhere. A one-sided sample therefore does not prove a single shared motive or a universal market imbalance.
That is why descriptive language matters. A careful analyst can say that a broker-defined retail sample shows directional concentration while avoiding the stronger claim that the wider FX market is aligned in the same way. The phrase retail positioning sample bias is useful because it keeps attention on selection, who is visible, who is absent and what type of behaviour the sample is more likely to capture.
A position book and an order book also need separate interpretation. A position book describes existing exposure within the sample. An order book describes pending interest within the sample. Neither establishes why a client entered, whether exposure is hedged elsewhere or whether visible orders will remain in place.
The same principle applies to public sentiment pages that use clear directional labels without explaining methodology. Research quality improves when the reader checks population, measurement, refresh process and exclusions instead of trusting the display alone.
Investing Bridge approaches sentiment as knowledge-first educational research. Its methodology can use OANDA books, FX option expiries and CFTC COT as distinct evidence sources within a broader multi-factor confluence framework. None is treated as a complete census of market activity, and the daily board at 09:30 EET is designed to organise context rather than turn a broker sample into a standalone answer.
A careful reader can apply the same discipline independently. Record what the source says, identify the sample, separate orders from positions and avoid turning a crowd description into a forecast.
Forex Sentiment Coverage Limits Across Time Horizons
The fourth check is to identify forex sentiment coverage limits across time horizons.
A broker snapshot may sit closer to observed client activity than a periodic positioning report, but that also makes it more sensitive to timing, refresh frequency and changes in the provider’s display. A slower report answers a different question. CFTC COT information concerns reportable futures markets and follows a formal publication process, so it offers a structured view of a defined futures population without becoming a live measure of OTC spot FX positions.
Neither time horizon is automatically superior. A faster sample may have narrower coverage, while a slower report may arrive after the observation point. The appropriate use depends on the question being asked.
These limits matter when a reader combines a broker snapshot with a periodic report. The sources may appear aligned, yet their populations and observation times remain different. Apparent disagreement can also reflect timing rather than contradiction. A research note should therefore preserve the timestamp or observation window for each source and state whether the input is updated continuously, periodically or only when published.
Time horizon also affects language. A short-lived broker observation can describe what is visible in that sample at that point. It does not support a timeless claim about positioning. Historical charts need similar care, because later displays may not perfectly match the original methodology or presentation.
A robust process therefore separates three ideas:
- Population, who or what is included.
- Timing, when the information was observed.
- Coverage, which market activity remains outside the source.
When these are kept distinct, the reader can combine evidence without pretending that the sources are identical.
This separation also improves historical review. Clear labels make it easier to see whether an old note described a narrow retail sample, a formal report from a different market or a hybrid comparison across evidence types. It also helps prevent unsupported claims about retail extremes. A one-sided observation may be notable, but it remains a description of sample exposure rather than a mechanical directional rule.
Sentiment Sample Comparison Without a Forecast
The fifth check is to conduct a sentiment sample comparison without a forecast.
This means asking whether the evidence is clearly described before asking what it might imply. The first question is not, “Where will price go?” It is, “What does this source actually measure?”
Start with the population. Identify the broker, entities, account types, instruments and participant categories included. Then identify the data object, such as pending orders, open positions, account direction, volume or another measure. Do not combine these categories casually.
Next, record the timing. Note when the observation was captured, how often it refreshes and whether it represents a snapshot or a reporting period. Then examine comparability. A broker sample, a futures positioning report and an options-related observation may all add context, but they do not describe the same market or population.
Finally, write the conclusion at the same level of certainty as the evidence. A broker-defined sample may show concentrated exposure within that sample. It does not automatically justify a broader claim about the entire market.
This approach also avoids ranking providers. The objective is to understand scope and choose the source that fits the research question. A trader studying client positioning may review a broker’s position book. A trader studying pending liquidity may review an order book. A researcher examining reportable futures positioning may consult the CFTC. Each source can be useful when its boundaries are respected.
The free EURUSD sentiment and COT research guide provides related context on combining sentiment concepts without reducing them to a single observation. Readers can also review the Investing Bridge research platform to understand the broader knowledge-first approach.
Investing Bridge does not present broker sentiment as a market-wide verdict. The daily board brings together defined evidence sources, including OANDA books, FX option expiries and CFTC COT, while making room for disagreement and uncertainty. The purpose is to explain why information matters, not to replace analysis with a simplistic crowd rule.
The same discipline applies to any educational chart or commentary. Ask whether the sample is current, whether the denominator is explicit, whether the source covers the relevant instrument and whether the observation is being used descriptively or predictively. For traders building a research journal, logging the population, data type, timestamp, stated methodology, known exclusions and interpretation limits can make later review more consistent and less reactive.
To explore these ideas through current educational research, inspect the free Investing Bridge preview without treating it as a promise of profits. The preview shows how defined evidence sources can be organised into a daily research process, with the board prepared at 09:30 EET. A 7-day free trial is available, followed by EUR 19 per month, subject to the platform’s current terms.
Keeping a Reviewable Forex Sentiment Sample Bias Research Note
A reviewable forex sentiment sample bias note preserves the source description beside the observed sample. Record the instrument, observation window and denominator exactly as documented. If a provider does not explain an exclusion, mark it as unknown rather than inventing an answer. Forex sentiment sample bias research improves when disagreement is kept visible: different populations can produce different observations without either becoming a global market census. Revisit the same questions during later review, and distinguish changes in client exposure from changes in the definition or refresh process of the sample itself.
Frequently Asked Questions
What is forex sentiment sample bias?
Forex sentiment sample bias occurs when information from a defined broker or platform population is treated as though it represents the entire FX market. A broker sample may describe its clients’ open positions or pending orders, but it does not automatically include every participant, venue or instrument.
How does retail positioning sample bias affect interpretation?
Retail positioning sample bias reminds researchers that retail clients are only one participant group. Their exposure can provide useful context, but it does not prove that the wider market is positioned the same way or that a reversal must follow a one-sided reading.
What are the main forex sentiment coverage limits?
Forex sentiment coverage limits include the provider’s entities, client types, instruments, denominator, update process and observation window. Broker sentiment population should therefore be identified before the data is compared with futures reports or other market sources.
How should I conduct a sentiment sample comparison?
A sentiment sample comparison should match population, instrument, data type and timing as closely as possible. Compare pending orders with pending orders and open positions with open positions, while keeping broker samples separate from broader claims about the FX market.
Not financial advice. Trading involves risk.
Investing Bridge provides educational market research, not investment advice. Trading involves substantial risk of loss.